
Home › Coverages › Landscape Contractor Insurance
Insurance for landscape construction, design-build and hardscape contractors
Landscape contractor insurance protects install, design-build and hardscape companies from the claims heavy work leaves behind, like a wall that fails after you leave, a gas line cut by a mini-excavator, or a regrade that sends water into a neighbor's yard. It usually combines general liability with completed operations, workers' comp, equipment and materials coverage, commercial auto, and the license and performance bonds your state or client requires.
- Since 2003
- 12+ A-rated carriers
- 28 states
- Independent agents
Start your landscaping insurance quote
Takes about a minute. A licensed agent follows up.
Licensed in 28 states · NPN 7642818 · Since 2003
Where landscape contractor insurance earns its keep
Install work gets hurt in bigger, slower ways than mowing does. A maintenance claim is usually a broken window this week. A landscaping contractor's worst claims involve heavy machines, open ground, tons of material and problems that surface a season or two after the crew has moved on.
Machines and open ground. A compact track loader, a mini-excavator and a loaded dump trailer can damage a driveway, a septic lid or a neighbor's fence in seconds. Open trenches and base-prep excavations sit on occupied properties for days, where kids and delivery drivers walk.
Weight and repetition. Your crews lift wall block, cap stones and pallets of pavers all day. Back and shoulder strains, crushed fingers and machine rollovers on slopes are the injuries workers' comp sees most on install crews.
What happens after you leave. Walls, grades and drains keep working long after the final invoice. When one fails and damages someone else's property, the claim can arrive a year or more later, and it lands on the liability policy in force when the damage happened.
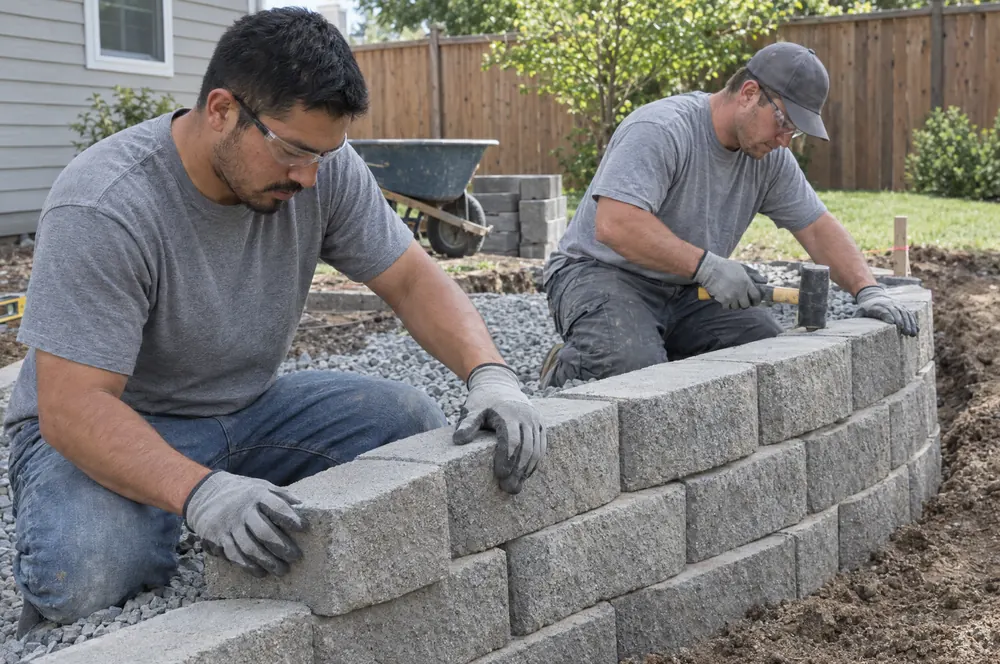
Example scenario: A three-person crew builds a segmental retaining wall about three feet tall along a sloped side yard in May. Two springs later, after weeks of rain, the wall bulges and pushes over the neighbor's cedar fence and crushes a garden shed. The neighbor's fence and shed are the kind of damage completed operations coverage is meant for. Rebuilding the wall itself is usually the contractor's own cost.
The landscaping contractor insurance stack
These are the lines most install and hardscape companies carry, roughly in the order they become necessary.
General liability with completed operations
Damage and injuries from your work, including problems that show up after the job is finished. General liability for landscapers
Workers' comp
Install crews usually rate under a landscaping installation code, and separate hardscape or sprinkler crews may carry their own. Workers' comp for install crews
Equipment and materials
Scheduled machines, rented loaders, and an installation floater for pavers, block and plants on the way to the job. Equipment and installation coverage
Commercial auto
Dump trucks, crew trucks and the trailers that haul your skid steer between jobs. Commercial auto for install fleets
Professional liability
For design-build plans, grading and drainage advice, and irrigation layouts your liability policy may exclude. Design professional liability
License bonds
The surety bond some states require before you can hold a landscape or hardscape license. Landscape license bonds
Performance and maintenance bonds
Bonds that guarantee a public or commercial install and the plant warranty period after it. Performance and maintenance bonds
Four things hardscape contractor insurance has to get right
Tree and shrub care on an install crew
Pruning, shrub care and small-tree work are often placed on a landscaping policy without trouble. Setting a balled-and-burlapped tree with a skid steer, shaping foundation shrubs, or raising a low canopy from the ground usually fits the landscaping class.
Climbing, removals, bucket and aerial work, and crane jobs are a different risk. They're usually rated as a separate tree-service class, and many landscaper policies limit them or leave them out. For comp in California, for example, pruning that needs a ladder, lift or climber is rated under the tree code, and so is the ground crew on that job. One online landscaping policy excludes stump grinding and tree removal entirely.
If a client asks you to drop a dead ash or climb a maple over the house, ask us before you take that job.
What general contractors, developers and homeowners will ask for
Install clients ask for more than maintenance clients do. A general contractor or developer usually wants to be added as an additional insured for both ongoing and completed work, because your patio or wall outlasts the project. On a large commercial or public new build, check whether the project has a wrap-up insurance program and whether your policy's wrap-up exclusion applies if you enroll.
Read the builder's risk terms too. The GC's policy may not cover your pavers, stone or plants before they're installed, or may leave landscaping out. That's the gap an installation floater is meant to close.
Homeowners and their states set rules too. In Virginia, retaining walls, grading and sprinkler installs over $1,000 need a contractor license with a landscape or irrigation specialty, and a $30,000 patio-and-wall job moves you from Class C to Class B. Our landscaping license guide covers the rest of our states.
Scaling an install company without coverage gaps
Each of these moves changes what an underwriter needs to know:
- Your first owned or rented machine. Schedule loaders and excavators by value, and make sure rented units are covered under your equipment policy before the rental counter asks.
- A dump truck. Heavier trucks are rated differently, and one rated at 10,001 pounds or more and used across state lines generally needs a USDOT number.
- A sprinkler crew. Underground sprinkler installation is usually rated under a plumbing code for comp, and some states license irrigation separately.
- A dedicated hardscape crew. Walls, patios and outdoor kitchens may be rated under a masonry or concrete code when one crew does them full time.
- Your first public bid. Sureties underwrite your capital, capacity and character, so get your financials in order before bid season.
In some states, install work also counts as construction for comp. Florida and Tennessee treat the landscape installation class as a construction class, which brings comp in with your first employee.
Frequently asked questions
Does landscape contractor insurance cover a retaining wall that fails?
Is hardscape contractor insurance different from landscaping insurance?
Do I need professional liability if I draw my own landscape plans?
Is a rented skid steer covered by my landscaping insurance?
Can my landscaping policy cover tree removal?
Related pages
Ready to see what you'd pay?
Independent agents, 12+ A-rated carriers, and a licensed agent back to you within one business day.